
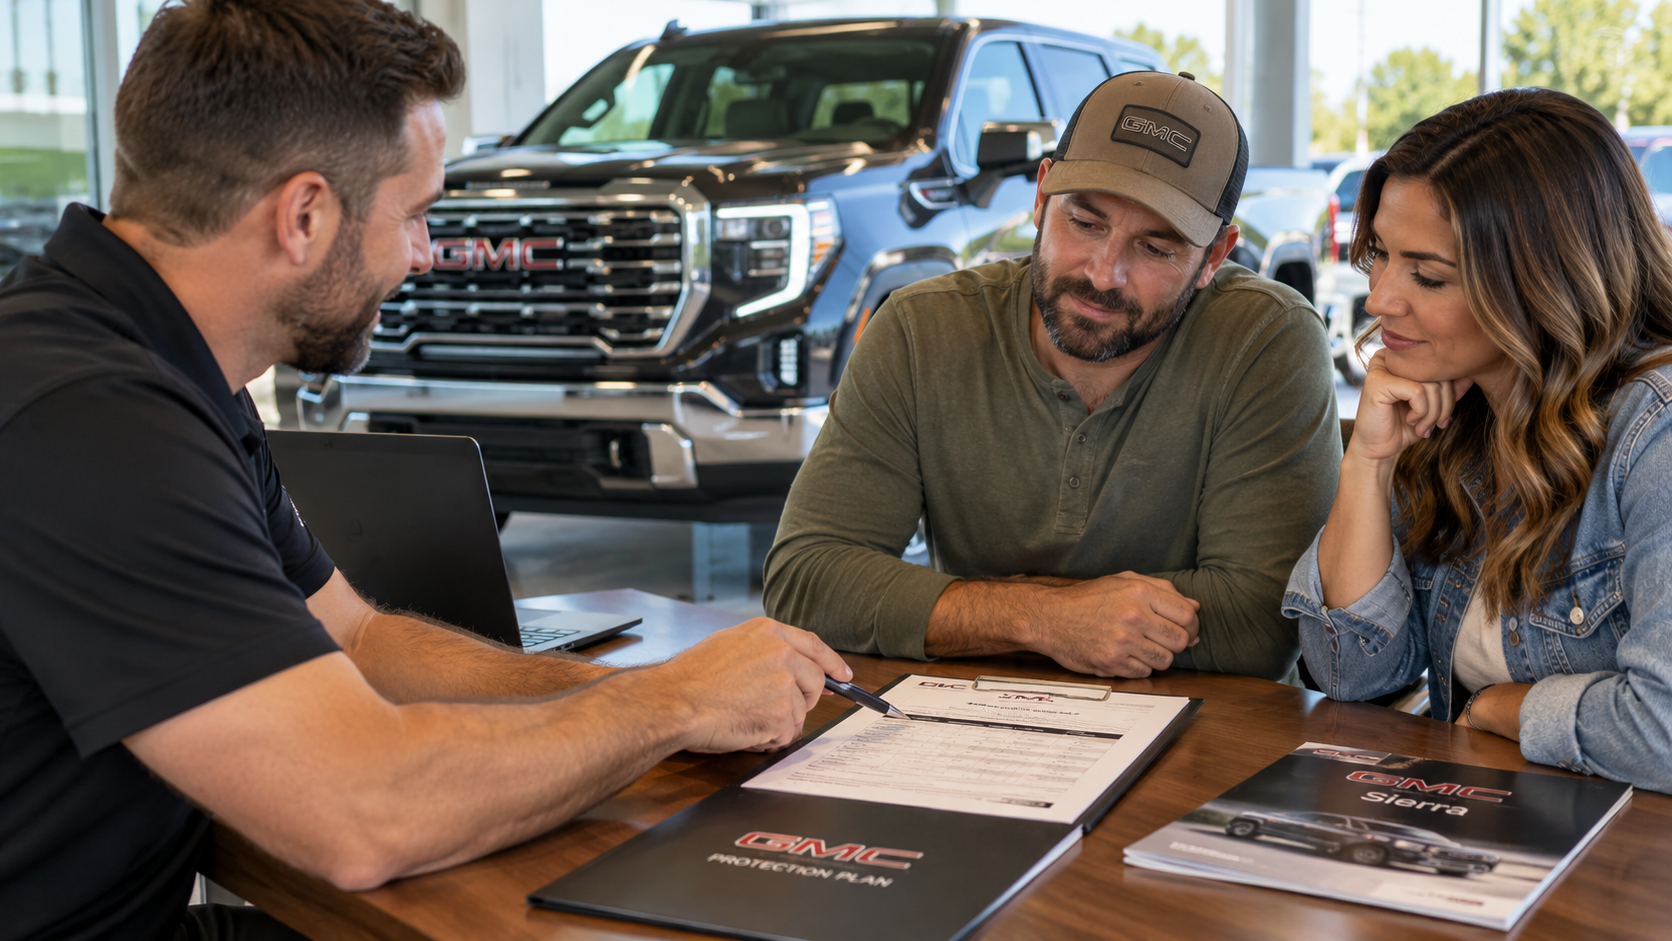
A GMC extended warranty can make sense when you plan to keep your Sierra beyond its factory coverage. The key is knowing what already comes with the truck. In addition, you need to know what an added plan covers. Towing, business use, mileage, and repair costs can all shape that decision. Therefore, a clear review now can prevent paying for duplicate protection later.
Start With the Sierra Coverage You Already Have
Every new Sierra begins with factory limited warranty coverage. GMC lists bumper to bumper coverage for three years or 36,000 miles. That warranty pays for covered repairs tied to defects in materials or workmanship. In addition, it includes towing to an authorized dealer for covered warranty repairs.
Powertrain coverage lasts longer than bumper to bumper coverage on many Sierra trucks. However, GMC notes that exact powertrain terms can vary by vehicle. For this reason, that detail matters before you add a GMC extended warranty. Your first question should be simple: what coverage remains on this specific Sierra today? The answer comes from the warranty booklet, vehicle records, and dealer documentation.
Before comparing added plans, verify these items:
- Confirm the in service date, current mileage, and remaining factory coverage for the Sierra.
- Additionally, review the exact powertrain term listed for the truck. Some configurations carry different mileage limits.
- Beyond that, check for separate coverage on emissions parts, corrosion, tires, or other listed components.
This review creates a clean starting point. Therefore, it shows where factory protection ends and where added protection could begin. In addition, it reduces the chance of paying for coverage that overlaps an active factory warranty.
What a GMC Protection Plan Adds
A GMC extended warranty is commonly discussed alongside the GMC Protection Plan. GMC offers Powertrain, Silver, and Platinum plan levels. Each level covers a different set of listed parts. Additionally, terms and deductibles vary by contract.
Powertrain coverage centers on major drivetrain parts. In addition, it includes listed engine, transmission, drive axle, and hybrid or electric components. Silver includes those areas, then adds several chassis and electrical groups. Moreover, Platinum adds a wider list that reaches into more electronic and technology related parts.
The main coverage groups break down this way:
- Powertrain focuses on listed engine, transmission, drive axle, and hybrid or electric components.
- Silver adds listed suspension, climate control, electrical, steering, and brake components.
- Beyond that, Platinum adds more listed technology, audio, navigation, parking assist, and display components.
Which GMC extended warranty level makes sense for a Sierra? Therefore, start with the parts you want protected after factory coverage ends. A driver focused on major drivetrain repairs may look closely at Powertrain. Someone keeping a truck longer may want broader component coverage. In addition, the contract should show covered parts, term, mileage limit, deductible, and exclusions.
Towing and Work Use Need Extra Review
Sierra trucks are frequently purchased for towing, hauling, jobsite travel, and business tasks. Those uses deserve a closer contract review. However, added coverage does not mean every repair tied to every form of truck use receives payment.
Does towing cancel GMC Sierra warranty coverage? Towing by itself does not create one universal answer. Factory warranty terms and service contract terms address different forms of coverage. In addition, GMC Protection Plan contract language references towing equipment requirements. A truck used for towing should have the correct factory or authorized equipment for its setup.
Work use requires another check. GMC Protection Plan contract language separates permitted use from certain commercial applications. Optional light duty commercial coverage may be required for eligible business use. Therefore, the contract and registration page should show whether that option was selected.
Before adding coverage to a working Sierra, ask:
- Is the truck equipped with the correct tow package for the trailer and load you plan to pull?
- Will the truck be used for paid business activity, fleet duty, delivery work, or another commercial purpose?
- Does the selected contract include any required commercial use option, surcharge, or exclusion?
These questions matter because the truck's role can change the contract review. By contrast, weekend towing may present a different contract scenario than daily business work.
Compare Cost With the Repairs You Want Covered
Is a GMC extended warranty worth adding to your Sierra? The answer rests on the contract price and your plans for the truck. Start with how long you expect to keep it. With that in mind, compare that timeline with factory coverage and the added plan term.
Mileage deserves equal attention. As a result, a high annual mileage total may reach a contract limit before the time limit. Another driver may own the truck for years while adding fewer miles. Therefore, the contract ends according to the terms written into that plan.
Next, compare the deductible with your repair budget. Therefore, a lower deductible can reduce what you pay during a covered repair. However, the plan price may differ. Still, a higher deductible can shift more of each covered repair cost back to you.
Also review the component list closely. Therefore, broader coverage makes more sense when added component groups match what you want protected. If your concern centers only on major drivetrain parts, a narrower plan deserves review. By contrast, broader coverage may deserve attention when electrical and technology repairs concern you.
Ask the Right Questions Before You Add Coverage
A GMC extended warranty should be reviewed like any other vehicle contract. The details matter more than the plan name alone. Therefore, before signing, read the agreement and ask the finance team to explain unclear language.
Start with the coverage start date. In addition, GMC states that Protection Plan terms begin from the contract purchase date and mileage. Contract terms can modify that timing. Therefore, active factory warranty coverage may overlap with part of the plan term. Ask how that overlap works for the plan you are considering.
Then confirm the term, mileage limit, deductible, covered parts, exclusions, and cancellation terms. Ask how claims are handled and where covered repairs can be completed. In addition, review towing and work clauses before purchase when either applies to your Sierra.
Beyond that, compare the plan against your own repair savings. Some drivers prefer a fixed contract cost. By contrast, others prefer to set money aside for future repairs. Neither path fits every Sierra owner.
Ross Downing GMC of Gonzales can also review your truck's current warranty status and service history. Therefore, that information gives you a stronger base for comparing added protection. If you are considering a new GMC Sierra 1500, review the plan alongside your mileage goals and towing needs. Also consider the years you expect to keep the truck. For this reason, a careful comparison makes the GMC extended warranty decision easier to understand before you sign.
For maintenance or repair questions, visit the Ross Downing GMC of Gonzales Service Department.